
Forced Appreciation vs. Natural Appreciation on Small Multifamily: Which Strategy Actually Moves the Exit Number More
Last updated: August 25, 2026
Published August 25, 2026 · Updated August 25, 2026
Forced appreciation vs natural appreciation which moves small multifamily exit value more is not a coin flip once you run the actual math on a 5-to-50 unit building. Forced appreciation, meaning deliberate increases to net operating income through rent bumps, expense cuts, and unit upgrades, typically moves the exit number more than natural appreciation, which is just the market drifting up around you while you sit still. That said, the two are not competitors so much as two different levers on the same machine, and the strongest exits I’ve studied blend both.
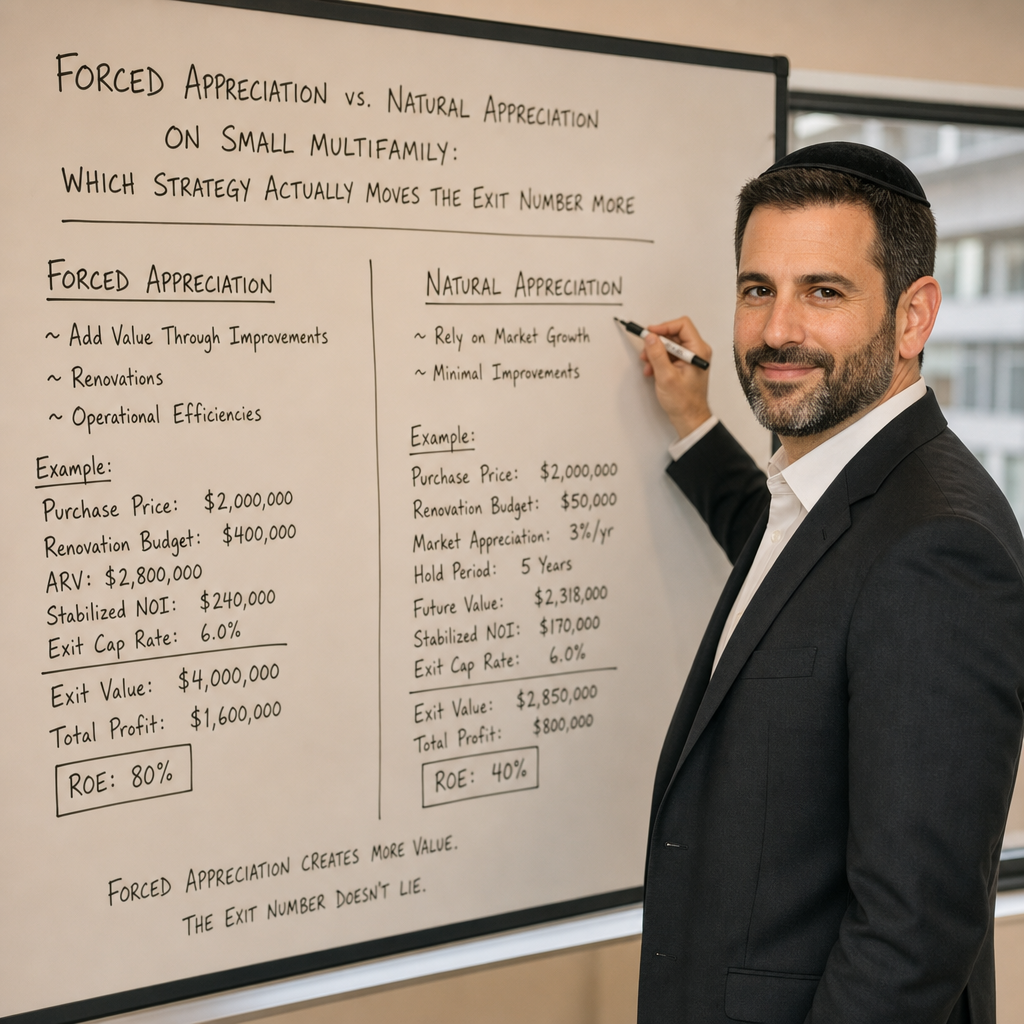
- Forced appreciation raises value through the income approach formula (Value = NOI ÷ Cap Rate), so a $12,000 annual NOI increase at a 6% cap rate adds roughly $200,000 to appraised value in an illustrative scenario.
- Natural appreciation depends entirely on the local market lifting rents or compressing cap rates, neither of which an operator on a small multifamily deal can control.
- On a 5-to-50 unit property, natural appreciation and cap rate compression tend to move slower and less predictably than a direct NOI push through rehab and rent repositioning.
- Small multifamily buyers typically use the income approach at exit, not comps, which is exactly why forced appreciation moves the needle harder than it would on a single-family flip.
- A blended strategy, buying below replacement cost in a market with upward rent trends, captures both levers at once and is how most seasoned value-add operators actually underwrite.
Forced Appreciation vs Natural Appreciation: Why the Comparison Matters More on Small Multifamily
Single-family homes get valued off comps. A four-plex or a twenty-unit building gets valued off income. That single difference is the whole reason this debate matters more here than anywhere else in real estate.
If you’re a small multifamily operator sitting on a 12-unit deal wondering whether to spend the next eighteen months on rehab or just wait for the market to carry you, the answer below changes how you spend your Monday morning. This is not a question for someone flipping one house. It’s for someone who owns a rent roll and has to decide where the next dollar of effort and capital actually goes.
The income approach means appraisers and buyers divide net operating income by a market cap rate to get value. Push NOI up, and value goes up on a multiple. Wait for the market cap rate to compress, and value also goes up, but you have zero control over when or if that happens. That’s the whole tension.
| Attribute | Forced Appreciation | Natural Appreciation |
|---|---|---|
| Who controls it | The operator, through rent, expenses, and unit condition | The market, through demand, rates, and cap rate trends |
| Typical timeline | 12 to 36 months of active rehab and lease-up | Multi-year hold, often 5 to 10 years to see meaningful gains |
| Capital required | Upfront rehab budget plus reserves for vacancy during turnover | Minimal beyond routine maintenance |
| Risk profile | Execution risk: budget overruns, contractor delays, lease-up drag | Market risk: rate hikes, oversupply, cap rate expansion |
| Exit value driver | Direct increase to NOI, which the income approach multiplies | Cap rate compression or rent growth outside your control |
| Best fit | Below-market rent rolls, deferred maintenance, mismanaged buildings | Already stabilized, well-run assets in a growing submarket |
| Predictability | High, tied to your own execution and underwriting | Low, tied to macro conditions and interest rate cycles |
Forced Appreciation on Small Multifamily
Forced appreciation means you go into a property and manually push NOI higher through rent increases tied to real upgrades, expense reduction, and better management. On a small multifamily property this is usually the single biggest lever available, because most 5-to-50 unit buildings on the market are underperforming in some obvious way. Rent below market. A laundry room nobody bothered to sub-meter. Water bills that could be cut with low-flow fixtures.
Here’s the illustrative math I look at, and this is how I evaluate deals, not investment advice. If a 10-unit property has an NOI of $84,000 and the market cap rate is 6%, it’s worth roughly $1,400,000. Push NOI to $96,000 through renovated units and tighter expense control, and at the same 6% cap rate that building is now worth approximately $1,600,000. That’s a $200,000 swing from operations alone, no market movement required.
The weakness is execution risk. Contractors run late. Vacancy during turnover eats into cash flow longer than planned. I’ve seen underwriting models assume a six-month renovation stabilize in four months on paper, then run nine months in the field because a permit sat on a desk. That gap costs real carrying cost, and it’s the part competitors writing about forced appreciation tend to gloss over.
“The deals that disappoint aren’t the ones where the market turned. They’re the ones where the operator underestimated how long it takes to actually collect the higher rent, not just post it.” – David Stern Team
Natural Appreciation on Small Multifamily
Natural appreciation is what happens to your exit value while you do nothing at all. Rents drift up because your area is growing. Cap rates compress because buyer demand for multifamily debt gets cheaper. Either one lifts the appraised value of a stabilized building without you touching a unit.
The strength here is obvious: zero rehab budget, zero tenant disruption, zero contractor headaches. If you bought a well-run, fully occupied 20-unit building at market rent and the region simply grows, you can watch the appraisal climb over a multi-year hold without lifting a finger beyond normal upkeep.
The weakness is that you’re a passenger, not a driver. Interest rate cycles move cap rates in both directions. A building that gained value from cap rate compression in a low-rate stretch can lose a chunk of that same value when rates rise and cap rates expand back out, even if NOI never changed. Freddie Mac’s own multifamily research has tracked exactly this kind of cap rate volatility tied to rate cycles over the past several years. Natural appreciation gives you upside you didn’t earn, but it can also take back value you never controlled in the first place.
Natural appreciation costs less effort but hands the steering wheel to the macro market. Forced appreciation costs more upfront work but keeps the exit number largely in the operator’s hands.
The Blended Approach: Buying for Both at Once
A blended approach means you underwrite a deal specifically because it has a forced appreciation angle, in a submarket that also shows real signs of natural rent growth. This is how most experienced value-add buyers I study actually structure their acquisitions, even if they’d never phrase it that clinically over coffee.
You get the guaranteed piece from your own execution, plus a tailwind if the market cooperates. I run scenarios like this through underwriting tools, including platforms like 8ight, to stress test what the exit number looks like if the rehab takes longer than planned and the market does nothing, versus if both go your way. Honestly, running the pessimistic case first is the habit that’s saved more deals than the optimistic one ever has.
The tradeoff is that you’re paying a premium to buy into a market with upward momentum, which means your entry cap rate is usually tighter. You’re betting on your own execution and getting a smaller discount for market risk. It’s the more disciplined path, and it’s also the harder one to find inventory for.
- Choose forced appreciation when you’re buying a mismanaged or deferred-maintenance small multifamily property below replacement cost, and you have the capital and patience for a rehab timeline.
- Choose to lean on natural appreciation when you already own a stabilized, well-run building and your priority is passive cash flow rather than active management.
- Choose the blended approach when you can find a value-add property in a submarket with documented rent growth trends, and you have the underwriting discipline to model both a stress case and a base case before you commit capital.
- Avoid forced appreciation if you don’t have reserves to cover a rehab timeline running long, since a stalled renovation erodes the exact NOI gain you were counting on.
Our Verdict
For an operator actively buying and repositioning small multifamily, forced appreciation wins the exit value question more often than not, because it’s the only lever you can pull on demand. Natural appreciation is real and it does add value over a long hold, but it’s a bonus, not a plan.
If you’re a buy-and-hold investor with a stabilized 8-unit building and no interest in construction management, leaning on natural appreciation and steady rent growth is a legitimate, lower-stress path. If you’re the operator willing to manage a rehab, a below-market rent roll, and a lease-up period, forced appreciation is the strategy that moves your exit number the most, and it’s the one you can actually plan around instead of hoping for.
This is how I evaluate the tradeoff on paper. It’s not investment advice, and it’s not a promise of any specific return on any property. Every deal has its own vacancy history, expense structure, and local rent ceiling that changes the math.
Our Take After Years of Underwriting Value-Add Multifamily
What surprised me early on was how many operators underweight the boring lever, expense reduction, in favor of the exciting one, rent increases. A $150 monthly water bill cut across ten units adds up the same way a rent bump does, but nobody brags about a new sub-metering system at a broker happy hour.
The pattern I notice most is operators who chase market timing on the natural appreciation side, trying to guess where cap rates are headed, when they’d be better served spending that mental energy on their own rent roll and expense ratio. You cannot control the ten-year Treasury. You can control whether unit 4B is renting for $200 under market because nobody’s raised it in three years.
If a friend asked me one thing to remember from all of this, it’s that the income approach rewards discipline, not luck. Closing on a Friday and skipping showings on Shabbat has never cost me a deal that was worth chasing. The deals worth having are still there Monday morning, and so is the spreadsheet.
Frequently Asked Questions
Does forced appreciation always beat natural appreciation on small multifamily exit value?
Forced appreciation typically adds more to exit value on 5-to-50 unit deals because it directly increases NOI, which the income approach multiplies by the inverse of the cap rate. It does not always win if a market experiences unusually sharp cap rate compression, but that scenario is outside an operator’s control and can’t be planned around.
How is small multifamily value calculated at exit?
Small multifamily properties are typically valued using the income approach, meaning appraisers divide net operating income by a market cap rate to reach value. A property with $84,000 NOI at a 6% cap rate would be valued near $1,400,000, illustrating why NOI moves matter more here than they do on single-family comps.
What’s the fastest way to force appreciation on a small multifamily property?
Raising below-market rents at natural lease turnover, cutting utility and vacancy losses, and completing targeted unit renovations are the three fastest levers, typically playing out over 12 to 36 months. Sub-metering water and adding coin or app-based laundry are common lower-cost expense-side moves operators overlook in favor of flashier renovations.
Can natural appreciation and forced appreciation work together on the same deal?
Yes, a blended strategy buys a below-market small multifamily property in a submarket already showing rent growth, capturing both the guaranteed NOI gain from renovation and any additional lift from market cap rate compression. This is the approach most experienced value-add buyers use, though it typically requires paying a tighter entry cap rate for the market tailwind.
Sources
- Multifamily cap rate trends and cycles – Freddie Mac Multifamily Research
- Income approach and appraisal methodology – Appraisal Institute
- Multifamily market commentary and rent growth data – Fannie Mae Multifamily Market Commentary
- Like-kind exchange rules relevant to multifamily exits – IRS Section 1031 Guidance
For more on how I underwrite value-add deals, see our breakdown of multifamily underwriting fundamentals, our notes on setting realistic renovation budgets, and our guide to planning a multifamily exit strategy. If cap rate math is new to you, start with how cap rates actually work.
🎧 Listen to article
- Small Multifamily Vacancy Rates and What They Actually Mean for a Value-Add Exit: Real Ranges, Not Projections
- Kitchen Renovation vs. Unit Layout Reconfiguration: Which Renovation Dollar Returns More on a Small Multifamil
- Small Multifamily Renovation Cost Breakdown: What Value-Add Repositioning Actually Costs in 2026
- What a Value-Add Multifamily Renovation Actually Costs Per Unit in 2026: Full Line-Item Breakdown by Scope
- A Reader Asked: “How Do You Know If a Value-Add Multifamily Deal Is Actually Worth the Renovation Budget?”


