
A Reader Asked: “How Do You Know If a Value-Add Multifamily Deal Is Actually Worth the Renovation Budget?”
Last updated: August 7, 2026
Published August 7, 2026 · Updated August 7, 2026
The hardest part of multifamily value-add investing isn’t finding the deal or hiring the contractors. It’s knowing when to walk away before you’ve sunk $900K into a building that won’t actually return your capital. I evaluate this by running five hard financial tests before any rehab dollar leaves the bank. None of them require luck, market timing, or developer wishful thinking.
The Short Answer
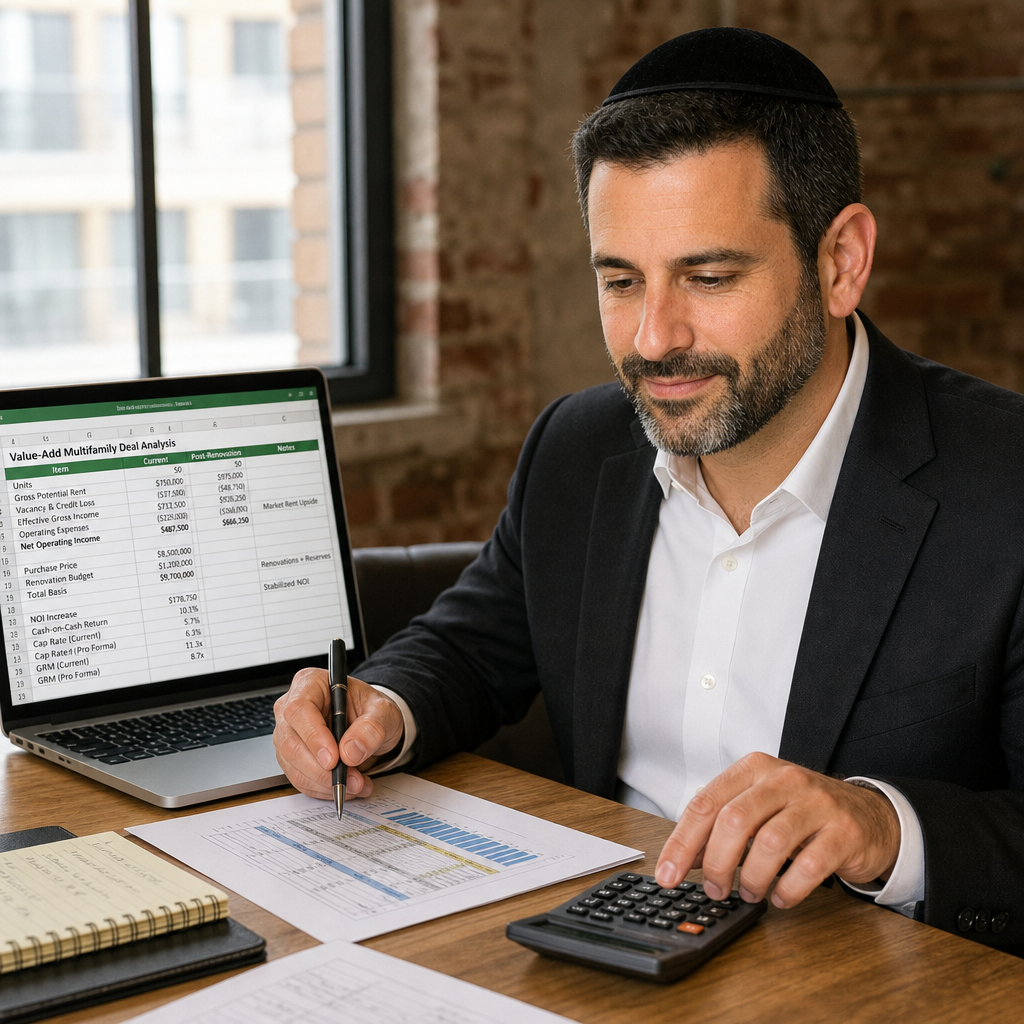
How do you know if a value-add multifamily deal is worth the renovation budget? Run the math three times: once using conservative rents, once using market rents, and once using the rents you’d need to hit your IRR target. If all three stress tests show a cash-on-cash return above 6%, and your rehab doesn’t exceed 30% of the purchase price, the deal is worth serious analysis. If only the “market rents” scenario works, you’re betting on perfect execution in a market that might soften. That’s a deal to pass.
The second test is timeline: if the contractor estimate puts you over 14 months for a mid-range rehab, the carrying costs and construction inflation will eat your margin before the first renovated unit is leased. The third test is comparable evidence: can you name three buildings in your area that actually rented at the stabilized rents your pro forma assumes? Not “theoretically could rent” – actually renting today.
The Full Answer
Test 1: Cash-on-Cash Return at Three Rent Scenarios
Most investors build a pro forma at one rent assumption – usually the highest defensible number. That’s how deals die quietly after closeup. You need to model three versions: conservative (10-15% below market), market (current comparable rents in your area), and optimistic (your target rents). Only the conservative scenario should pencil out to a 6% minimum cash-on-cash return.
Here’s what this looks like in practice. Say you’re analyzing a 20-unit building. Purchase price $1.6M. Stabilized rent target is $1,450/month. Your total invested capital (purchase plus rehab plus soft costs) is $2.3M. That means you need a stabilized NOI of at least $138K annually (6% × $2.3M) to hit your minimum return threshold. Multiply that by 8.5 (a typical cap rate for stabilized multifamily assets), and your stabilized value needs to be around $1.17M just to break even on your invested capital. If market comps show $1,200 – $1,300 stabilized value, you have margin. If they show $1.1M, you’re betting on either faster rent growth or a cap rate compression that no one can guarantee.
Run your pro forma at 85% occupancy in the conservative scenario, not 95%. Assume a 7% annual rent growth in the optimistic case, not 10%. If the conservative scenario still works, you’ve proven the deal survives the most likely outcome.
Test 2: The Renovation Budget-to-Purchase-Price Ratio
If your rehabilitation budget exceeds 30-35% of the purchase price, you’re no longer doing a value-add renovation. You’re doing a repositioning, which is a completely different risk profile. The budget ratio tells you how much value creation you’re asking the rehab to deliver.
A 20-unit building at $2M costs $100K per unit to acquire. A $600K rehab is $30K per unit – typical for unit interiors, common area updates, and system fixes. A $1.2M rehab at $60K per unit is much heavier and typically includes structural work, major HVAC replacement, or a significant footprint redesign. Both can work, but the 60% ratio is riskier because it requires more precise execution and leaves less room for budget overruns.
“If the rehab budget eats more than one-third of the acquisition price, ask yourself whether the problem is actually fixable at a reasonable cost, or whether you’re just buying into someone else’s structural headache.” – David Stern Team
Track the budget breakdown too. If 60% goes to unit interiors, 20% to common areas, and 20% to infrastructure, you’re spreading risk across many revenue-generating improvements. If 70% goes to one system (like a foundation repair or a full roof), you have a single point of failure that, if it runs over, blows your entire margin.
Test 3: Timeline Risk and Carrying-Cost Impact
A well-managed multifamily rehab takes 10-14 months from close of escrow to first stabilized occupancy. Anything longer and your carrying costs (debt service, property taxes, insurance, vacancy losses) begin eating into your equity spread like rust.
Here’s the math. You’re carrying a $1.8M construction loan at 7.5% interest on a 20-unit rehab. Monthly carrying cost is roughly $11,250. If your rehab timeline extends from 12 months to 16 months (a very common overrun), you’ve added $45K in interest alone. If you’ve also underestimated the rehab budget by 8-10% (the industry norm), you’re now $50-80K underwater on your projected equity return before you’ve leased a single renovated unit.
Ask your GC for a timeline with named milestones, not a vague “approximately 12 months.” Get three recent job references where the timeline was met within 2 weeks. Call them. If they say “it took about 18 months” and wave their hand, that contractor’s estimate cannot be trusted.
Test 4: Comparable Rent Validation – Do These Rents Actually Exist?
The biggest mistake I see is pro forma rents that are 5-8% above current market comparables in your area. Investors rationalize it as “market growth” or “our units will be nicer.” Neither argument holds. If your stabilized rent assumption is $1,550 and the three newest comparable buildings in your area are stabilizing at $1,485 – $1,510, your unit will not command a $65 premium just because you put in new flooring and repainted.
Use CoStar, your local MLS data, or recent lease comps from similar-unit buildings within 0.5 miles of the subject property. Pick three buildings that have completed renovation in the last 18-24 months and were stabilized for at least 6 months. What are they actually renting for, not what they’re asking? Market rent is what a tenant will sign a lease for at 90%+ occupancy on a move-in ready unit – not the aspirational asking rent on a small percentage of premium units.
If you cannot name three buildings in your area that are actually renting at or above your pro forma rent, adjust your assumption downward. The market is the market.
Test 5: Exit Cap Rate Reality Check
Your exit assumption is the number that moves everything. If you’re projecting an 6.5% exit cap rate (to justify a $2M valuation on $130K NOI), make sure that cap rate actually exists in your market today. If the current average cap rate for stabilized assets is 7.5%, you’re assuming 100 basis points of cap rate compression in 3 years. That’s a bet on interest rates falling and institutional capital flooding into your area. That’s not analysis; that’s hope.
Use the cap rate that trades today in recent arm’s-length sales of comparable assets as your exit assumption, not the cap rate you wish would exist. If today’s stabilized assets trade at 7.2% and you need a 6.5% exit cap to make your numbers work, your deal is dependent on external market forces you cannot control. That makes it speculative, not value-add.
Test the deal at conservative rent assumptions, ensure the rehab stays under 30% of purchase price, confirm the timeline with verified GC history, validate rents against real market comps, and use today’s cap rates for your exit. If all five tests pass, you’re analyzing a genuine value-add opportunity. If three or fewer pass, you’re gambling.
Related Question We Often Hear
When the Answer Is Different
If you’re in a rent-growth corridor where rents are appreciating 4-6% annually and institutional capital is actively buying assets in your area, the bar for a value-add deal is slightly lower. You can afford to assume a cap rate compression because the market data supports it. But even then, the five tests above still apply. Never skip the conservative rent scenario or the timeline reality check just because the market feels strong.
This analysis is how I look at deals – not investment advice. Every deal carries risk, and past performance in one market doesn’t predict future results in another. Always consult a licensed real estate advisor or attorney in your jurisdiction before committing capital.
Frequently Asked Questions
What’s the minimum cash-on-cash return I should require before committing to a value-add multifamily deal?
A minimum 6% cash-on-cash return in year one is the floor for multifamily value-add deals in most markets. This gives you a margin above borrowing costs and accounts for the execution risk of the renovation. If you’re stabilizing at lower occupancy (85% rather than 95%) or the market is softer than average, require 7-8% to offset that risk. Never underwrite a deal where the conservative scenario yields less than 5% cash-on-cash – that’s margin erosion waiting to happen.
How do I stress-test for construction delays without being overly pessimistic?
Build two scenarios: one where the timeline holds (contractor hits milestones within 1-2 weeks) and one where it slips by 4-6 months (typical for mid-range rehabs). Calculate the additional carrying costs and how much margin they consume from your projected return. If a 6-month delay cuts your year-one cash-on-cash return from 6.5% to 4%, the timeline risk is too high. Ask yourself if you have capital cushion to absorb that slippage without hitting your lenders’ default covenants.
Should I always assume a 20% contingency on the contractor’s rehab estimate?
For a standard mid-range multifamily rehab with no major structural unknowns, a 10-15% contingency is typical. If the building has deferred maintenance, old systems, or potential foundation issues, push it to 20%. Never assume a contractor estimate is final. Ask your GC to break down the rehab scope into 4-5 major categories (units, common areas, systems, exterior, parking) so you can track where overruns are most likely. Units rarely come in over budget; systems and exterior are where surprises live.
How current should my comparable rent data be to trust it in the underwriting?
Use rent data from the past 6-12 months for comparable buildings that stabilized or renewed leases within that window. Anything older than 12 months is outdated in a dynamic market. If comparable buildings haven’t had lease renewals in 18+ months, you’re flying blind. In that case, adjust your pro forma rent down 2-3% below the last known comp as a safety factor, because market conditions may have shifted since those rents were set. Always prefer recent data from buildings like yours – same age, same unit count, same amenity level, same general area.
Sources
- Multifamily asset valuation and cap rate compression trends – CoStar Group, Inc.
- Construction cost inflation and timeline risk in commercial real estate – U.S. Bureau of Labor Statistics
- Debt service and carrying cost modeling for development projects – Fannie Mae Multifamily Guidelines
- Value-add real estate investment strategy fundamentals – NAIOP (National Association of Industrial and Office Properties)
David Stern
Multifamily developer and value-add investor. I show you how to underwrite a deal that actually works.


