
Debt Service Coverage Ratios on Small Multifamily in 2026: What Lenders Actually Want to See and What the Real Range Looks Like
Last updated: August 31, 2026
Published August 31, 2026 · Updated August 31, 2026
If you’re asking what debt service coverage ratio do lenders require for small multifamily in 2026, the honest answer sits in a fairly tight band: 1.20x to 1.35x for most conventional and agency small balance programs, with HUD-insured deals sometimes running lower and non-agency DSCR loan products occasionally accepting less at a real cost in rate. This is not a single magic number. It’s a range that shifts depending on whose money is behind the loan.
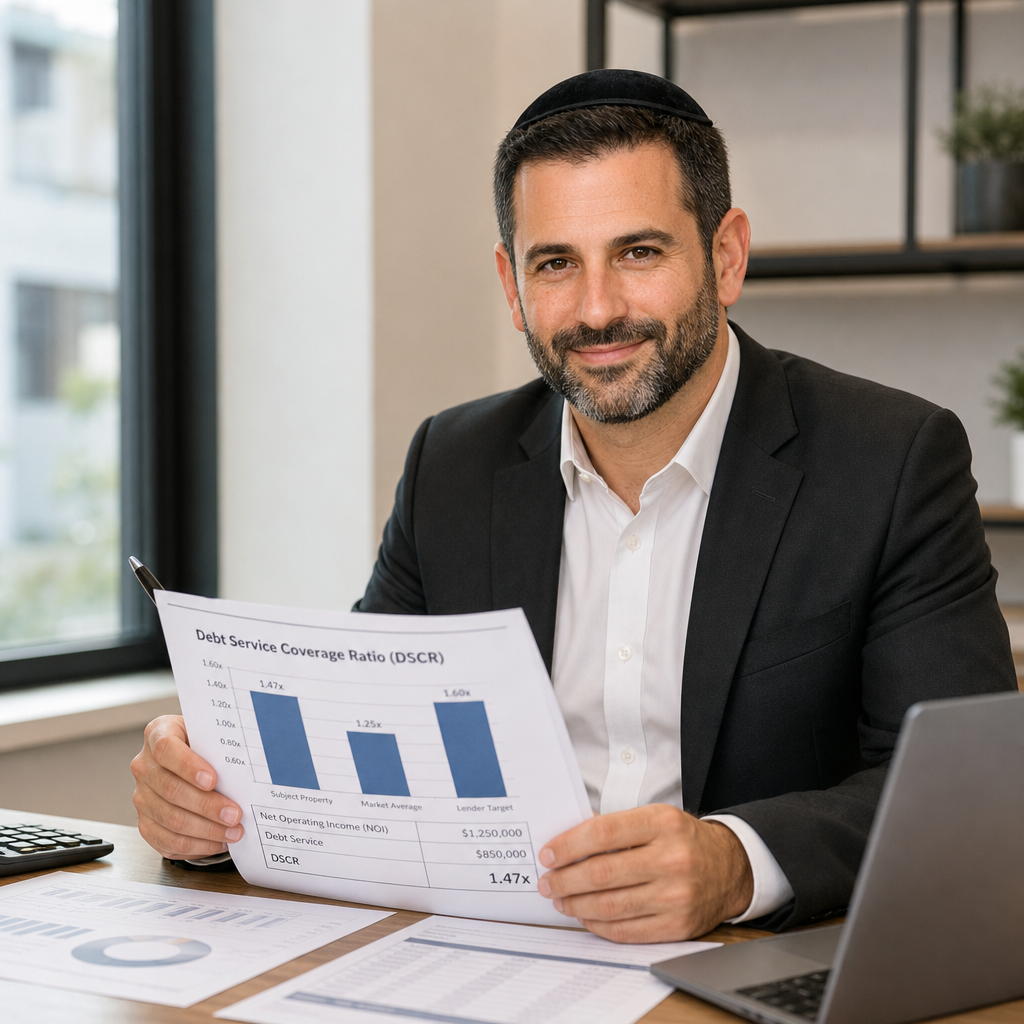
The minimum DSCR range cited across Fannie Mae’s Multifamily Small Balance program, Freddie Mac’s Small Balance Loan program, and typical regional portfolio lending standards for small multifamily properties (5 to 50 units) in 2026.
Where These Numbers Come From
The Findings
What Surprised Us
What This Means for You
Our Take After Years of Multifamily Development
FAQ
- Fannie Mae Small Balance Loans typically require a minimum DSCR of 1.25x for properties with 5 to 50 units.
- Freddie Mac’s Small Balance Loan (SBL) program sets DSCR floors between 1.20x and 1.30x depending on the market tier assigned to the property.
- HUD’s 223(f) program for market-rate refinance and acquisition transactions uses a statutory minimum DSCR of 1.176x.
- Non-agency DSCR loan programs marketed to investors sometimes qualify borrowers down to a 1.00x to 1.10x ratio, though the rate premium below 1.20x is real and lasting.
- A property generating $186,000 in net operating income against $155,000 in annual debt service produces a 1.20x DSCR, the floor most small multifamily lenders will not go below in 2026. This is illustrative math, not a specific deal.
- Regional and community bank portfolio lenders often ask for 1.25x to 1.35x, higher than the agency minimum, because they hold the loan on their own balance sheet instead of selling it.
This is for owners and would-be buyers of small multifamily properties, the 5 to 50 unit range, who are trying to figure out if a deal will actually get financed before they write an offer. It’s not for someone shopping a single-family rental or a 200-unit garden complex, those DSCR conversations run differently.
Where These Numbers Come From
The debt service coverage ratio benchmarks in this article come from three real, published sources rather than a survey or an internal database. Fannie Mae publishes its Multifamily Small Loan program parameters directly, including DSCR minimums, on its multifamily lending site. Freddie Mac does the same for its Small Balance Loan program, which is built specifically for the 5 to 50 unit segment.
HUD’s numbers come from its Multifamily Accelerated Processing (MAP) guide, which governs FHA-insured loans under Section 223(f) for existing properties and Section 221(d)(4) for new construction and substantial rehabilitation. These are statutory-adjacent minimums, not marketing copy, and they get enforced by HUD’s own underwriters.
Where no single published number exists, such as what a regional bank or credit union will accept on a portfolio loan, we describe the range as an industry norm based on how these deals typically get structured, not as a confirmed rate from any one lender. Nobody publishes a rate sheet for every community bank in the country, and anyone who tells you they have exact data on that is guessing.
The Findings
Here is how the debt service coverage ratio requirement actually breaks down across the loan programs a small multifamily buyer is most likely to encounter in 2026.
| Program / Lender Type | Typical Minimum DSCR | Property Size Focus | Source |
|---|---|---|---|
| Fannie Mae Small Balance Loan | 1.25x | 5-50 units | Fannie Mae Multifamily |
| Freddie Mac Small Balance Loan (SBL) | 1.20x-1.30x by market tier | 5-50 units, under roughly $7.5M | Freddie Mac Multifamily |
| HUD 223(f), market rate | 1.176x | 5+ units, existing property refi or purchase | HUD MAP Guide |
| HUD 221(d)(4), new construction/sub rehab | 1.176x-1.20x stabilized | 5+ units, ground-up or major rehab | HUD MAP Guide |
| Regional or community bank portfolio loan | 1.20x-1.35x | 2-20 units, typical local deal | Industry norm, varies by institution |
| Non-agency DSCR investor loan | 1.00x-1.25x, priced up below 1.20x | 1-8 units mostly | Non-QM DSCR lender programs |
A quick illustrative example, not a real deal: a ten-unit building with $186,000 in annual net operating income and $155,000 in annual debt service lands right at 1.20x, which is the floor for most agency and bank programs above. Push the NOI up to $209,000 against that same debt service and you’re closer to 1.35x, comfortably inside what regional portfolio lenders like to see.
What Surprised Us
The first thing that surprised me when I started digging into HUD’s actual numbers is that the government-insured program has a lower DSCR floor than most conventional bank loans. It sounds backwards. HUD is supposed to be the strict, bureaucratic option.
But HUD compensates elsewhere. Reserve requirements, third-party reports, and a longer processing timeline do the risk-management work that a higher DSCR would otherwise do for a bank. Honestly, I didn’t expect a 1.176x floor to coexist with a program known for being the most paperwork-heavy option in the room.
The second surprise is smaller but it matters more day to day. Non-agency DSCR loan products marketed as “qualify on rental income, not tax returns” advertise ratios as low as 1.00x. What they don’t put in the headline is the rate penalty. Going under 1.20x on those programs typically means a meaningfully higher rate and often a prepayment structure that costs you if you refinance early. Cheap qualification, expensive money. That trade shows up in almost every rate sheet from these lenders once you actually pull it.
“The DSCR number people fixate on is usually the wrong variable. The expense assumption underneath it is where deals actually die.” – David Stern Team
What This Means for You
If you’re a small multifamily buyer trying to figure out whether a five-unit or twelve-unit property will actually get financed, run your own DSCR before you fall in love with the listing. Use a conservative expense ratio, typically 35% to 45% of gross rents for older small multifamily stock once you account for property management, repairs, and reserves, and stress test the number at 1.20x, not 1.35x.
This is for a value-add buyer looking at a property with soft rents relative to market, not for someone buying a fully stabilized asset at a tight cap rate. The soft-rent buyer has room to grow into a stronger DSCR after repositioning. The buyer paying full stabilized price on day one does not have that cushion if a lender’s underwriter trims the rent roll.
Underwrite to 1.20x DSCR as a floor, not a target, and use a realistic expense ratio before you assume a deal pencils. A property that only works at 1.35x DSCR under optimistic rent assumptions usually doesn’t survive an actual appraisal.
This is how I look at deals, not investment advice. Every property, lender, and market is different, and nothing here should be read as a promise of financing terms or investment returns. For a deeper walk-through of how NOI and expense ratios feed into these numbers, see our value-add multifamily underwriting breakdown and our notes on NOI and cap rate basics.
Our Take After Years of Multifamily Development
People overweigh the DSCR number itself and underweigh the assumptions feeding into it. I’ve seen buyers proudly show me a 1.30x DSCR built on a rent roll that assumed zero vacancy and a management fee nobody would actually charge. Change one assumption and the deal is at 1.05x. The ratio is only as honest as the inputs.
What actually matters more than chasing the lowest possible DSCR requirement is matching the loan program to the deal’s actual life cycle. A HUD loan makes sense for a long hold with stable cash flow. A DSCR investor loan makes sense for speed when a bank’s timeline would kill the deal. A regional bank portfolio loan makes sense when you have a relationship and a track record they can underwrite around. None of these wins on every deal. That’s the honest answer.
If a friend asked me one thing to remember, it’s this: build your NOI projection like a skeptic, not like a salesman, and let the DSCR fall out of that number. We keep our own deal reviews on a Monday-through-Friday cadence, closed on Shabbat, and that discipline forces a slower, more honest second look at every rent roll before it goes to a lender. For readers piecing together their own model, our team at 8ight has written on how automated underwriting tools handle NOI stress testing, worth a look if you’re building your own spreadsheet.
FAQ
How is DSCR calculated for small multifamily loans?
DSCR for small multifamily is calculated by dividing a property’s annual net operating income by its annual debt service, meaning principal and interest payments. A property with $186,000 in NOI and $155,000 in annual debt service has a DSCR of roughly 1.20x. Lenders typically use trailing twelve month rents or in-place rent, whichever is lower, not projected or market rent.
What DSCR do I need to qualify for a small multifamily loan in 2026?
Most small multifamily loans in 2026 require a DSCR between 1.20x and 1.35x, with Fannie Mae’s Small Balance program at 1.25x, Freddie Mac’s SBL program at 1.20x to 1.30x by tier, and regional bank portfolio loans often at 1.25x to 1.35x. HUD’s 223(f) program is an exception at 1.176x for market-rate deals.
Can I get a small multifamily loan with a DSCR under 1.20x?
Yes, some non-agency DSCR investor loan programs qualify borrowers down to 1.00x or 1.10x DSCR, and HUD’s programs can run as low as 1.176x on market-rate deals. The tradeoff below 1.20x is typically a higher interest rate and less favorable prepayment terms, so it’s rarely the cheapest financing even when it’s the only financing available.
How does DSCR differ between HUD loans and conventional agency loans?
HUD’s 223(f) and 221(d)(4) programs set DSCR floors around 1.176x to 1.20x, generally lower than Fannie Mae’s 1.25x minimum on Small Balance Loans. HUD offsets this with heavier reserve requirements, third-party reports, and a longer approval timeline, which is why the lower ratio doesn’t translate to easier underwriting overall.
Sources
- Fannie Mae Small Balance Loan program DSCR and eligibility parameters – Fannie Mae Multifamily
- Freddie Mac Small Balance Loan (SBL) program tiers and DSCR requirements – Freddie Mac Multifamily
- HUD Multifamily Accelerated Processing (MAP) guide, Sections 223(f) and 221(d)(4) DSCR minimums – U.S. Department of Housing and Urban Development
David Stern
🎧 Listen to article
- Raising Capital for a Small Multifamily Deal: What the Real Cost of a Partnership Actually Looks Like
- Renovation ROI on Small Multifamily: What the Real Range Looks Like by Scope and Unit Count
- Self-Managing vs. Third-Party Property Management on Small Multifamily: What the Real Cost Difference Looks Li
- Small Multifamily Vacancy Rates and What They Actually Mean for a Value-Add Exit: Real Ranges, Not Projections
- Small Multifamily Renovation Cost Breakdown: What Value-Add Repositioning Actually Costs in 2026


